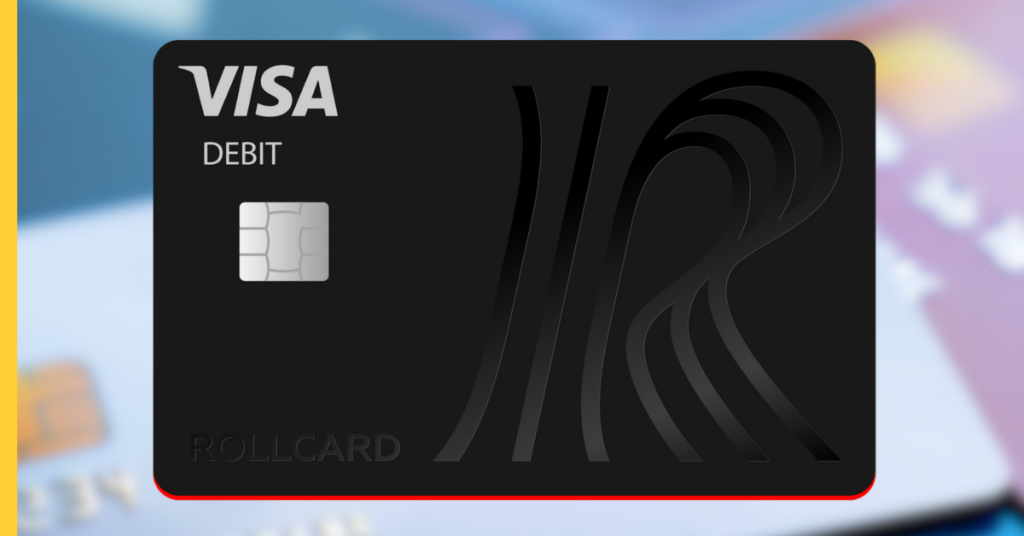
The new ‘Rollcard’, launched in partnership with Cross River Bank, separates the gambling funds of high rollers from their everyday finances
Grandstand, formerly known as Gambling.com Group, has launched a Visa debit card specifically targeted at high-spending gamblers.
The ‘Rollcard’ is being issued by the Cross River Bank and allows high-rollers to keep their gambling funds separate from their everyday finances.
Sports bettors, casino players and prediction market traders are all mentioned as potential users of the fintech solution.
Grandstand CEO and co-founder Kevin McCrystle commented: “Serious players deserve a dedicated financial product built for how they play.”
Facilitating high spending
A key feature that may encourage high-spenders to take up the option of getting themselves a Rollcard is the cashback reward programme.
These incentives mean bettors can earn money if they meet qualifying spending levels at certain sportsbooks, casinos and prediction markets.
Players are also enabled to move up to $1m per business day, removing the friction that may be introduced if attempting to transfer such sums from a normal bank account.
Typically, debit cards would max out at a far lower sum than that.
According to McCrystle: “Financial tools have not kept up with the growth in sports trading and gaming, and Rollcard solves the problems players face managing their bankroll.”
Encouraging control
The positioning of the product also suggests that the separating out of funds will give users an extra degree of control over their spending.
Security-wise, the backing of Visa lends a level of payment expertise and integrity that will likely give potential card-holders confidence in the programme.
While the card allows for high-spending, there are customisable controls in place and cooling-off periods built in.
Contradiction?
With all of the above in mind, the mechanics of the card seem to be pulling in two different directions.
The facilitation of high spending, alongside the provision of checks and controls are not necessarily mutually exclusive forces, but getting the balance wrong is an easy way to draw regulatory scrutiny.
Will Mace of Mindway AI hailed it as a potentially powerful player safety tool, given its ability to apply controls no matter what operator the player is engaging with.
These could be easily bypassed however, and Mace tells NEXT.io that it relies on the player not switching between payment methods to have real value.
Joseph Gaunt, Director at TEC+ Consulting, agrees that using separate payment methods is “common punter behaviour,” but notes that the product positioning reflects that “affordability is relative to the person.”
He adds: “There is no reason why they should not be able to bet high stakes and have an appropriate payment method.”
Will it be challenged?
So, a remaining question, before the Rollcard becomes widespread, is in which jurisdictions it could encounter the most hurdles.
Jeremy Eberwein is the chief of the technology division at the Nevada Gaming Control Board and told NEXT.io: “The Nevada Gaming Control Board is not aware of this product’s use in Nevada, but our general understanding is that the issuer of the card, Cross River Bank, would need to meet all federal KYC requirements for a financial institution, which would be on par with or exceed most gaming regulatory requirements for KYC, as well as address the Responsible Gaming requirements in each respective jurisdiction.”
McCrystle appears confident that it will become widespread, capitalising on Grandstand’s existing audience relationship and the gap in the fintech market that it has identified.
He said: “We have spent two decades building the brands millions of consumers trust across sports and gaming, and that has shown us the friction they face.”