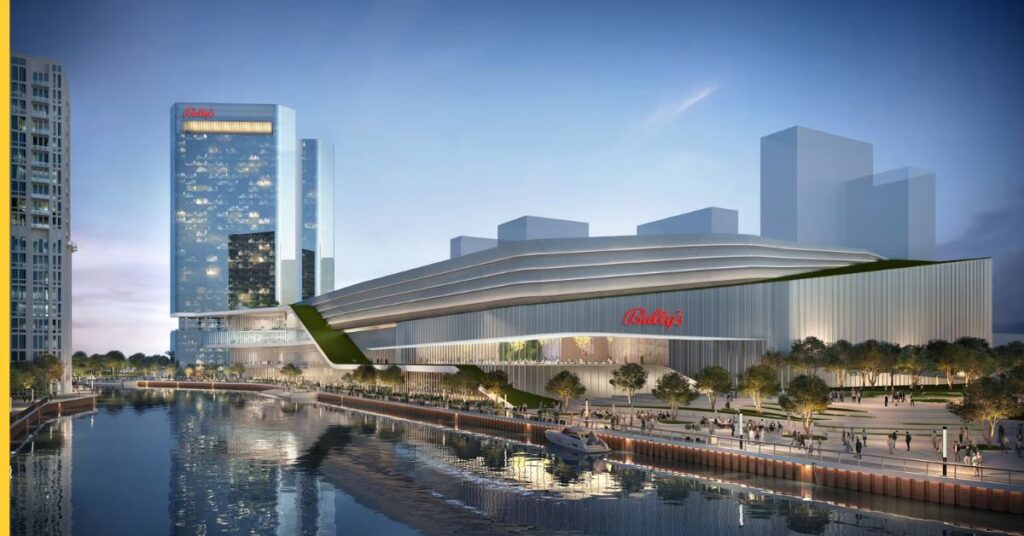
Bally’s Corporation secured $2.07bn from REIT Gaming and Leisure Properties, Inc (GLPI) to construct its planned downtown Chicago casino project (pictured) on Friday (12 July).
The revised project will see a GLPI affiliate purchase the underlying real estate and amend the rent to $20.0m per annum, reflecting the land’s purchase price.
The lease will also involve a clause allowing GLPI to provide up to an additional $940m of construction financing for the project’s hard costs through monthly draws.
It follows the Chicago City Council approving Bally’s plan to build a casino resort in the Windy City in May 2022.
Bally’s chairman Soo Kim said: “Our agreements with GLPI fulfill the construction financing requirements, allowing us to bring the Bally’s Chicago permanent casino and entertainment complex to River North by the fall of 2026.
“We are delighted to continue our strong partnership with GLPI and to leverage its skilled resources and 30 years of experience developing and constructing successful gaming facilities.
“This is an amazing partnership that continues to pay strong dividends for both parties.”
On Friday, Bally’s also released new renders of the project, although these will be subject to revision and are pending approval from the Chicago Department of Planning & Development.
The lease will have an initial term of 15 years, with a specified number of successive options for renewal.
Bally’s said the amounts funded by GLPI will result in additional rent capping out at 8.5% added.
The deal also includes a provision for GLPI to acquire and lease back underlying property interests at Bally’s Kansas City and Bally’s Shreveport for $395m.
This is in exchange for $32.2m in initial annual rent with annual escalators consistent with GLPI’s master agreement.
The casino group said it intends to use all the proceeds from the transaction to repay amounts owed under its $630m revolving credit facility and for general corporate purposes.
GLPI can call $735m Twin Rivers sale from Oct 2026
Bally’s also reiterated its intention to sell and lease back its Twin River Lincoln property to LPI prior to the end of 2026 for $735m, with an initial annual rent of $58.8m.
As part of the deal GLPI will be granted a right to call to the transaction beginning in October 2026, which coincides with the scheduled maturity of Bally’s debt agreement.
All transactions are subject to required regulatory approvals, Bally’s said.
Overall, GLPI will provide in aggregate up to $2.07bn of financing to Bally’s, which the casino said further cemented the companies’ long-term strategic alliance.
GLPI chairman and CEO Peter Carlino added: “We are excited to partner in Bally’s Chicago marquee development project which will be the flagship of Bally’s platform, and an iconic addition to the Chicago skyline.
“We are appreciative of Bally’s trust in GLPI as its selected strategic financing partner.
“This is a natural extension of our corporate growth strategy to work closely with tenants and finance the construction of development projects, and to pursue built-to-suit partnerships in the gaming sector where we have experience and can contribute GLPI’s extensive, proven development and construction capabilities.
“Strategically, this is a means to grow our asset portfolio within the gaming sector that we know well and allows us to create value for our shareholders.
“We have strong confidence in Bally’s team and will be working hand-in-hand with Bally’s to bring this project to fruition on time and on budget.”
Analysts highlight high Bally’s leverage after Chicago deal
The deal was well received by the market, which rewarded Bally’s with close to a 10% boost to its share price following the deal.
Analysts at JMP Securities highlighted that durable GLPI tenant relationships continue to provide compelling off-market investments that offer meaningful bottom-line upside.
They added that the deal structure should deliver resilent cash flows across cycle, and as such, maintained the REIT’s Market Outperform rating and $53 price target.
In a separate note, JMP said Bally’s lease-adjusted leverage will hover at 6.5x through to completion of the Chicago project.
This would make Bally’s the most leveraged gaming stock covered by JMP during the time period.
The analysts added: “Our back of the envelope math leads us to believe 2027 will act as a deleveraging event to around 5.5x if the Lincoln real estate is sold, while the ramp of Chicago, beyond its current run-rate at the temporary casino, will only deleverage BALY further.
“That said, we do not expect investors to give the company credit for the outlook into 2027 with the macro backdrop, questions still remaining in Las Vegas, and the risk to underlying execution.”
These leverage concerns were echoed by analysts at Truist, who argued higher leverage has driven public equity investor concerns.
They said: “BALY has among the highest leverage across our coverage (PF net leverage pre-opening for Chicago would be >7x), and likely stays at elevated levels for sometime if LV and/or NY developments follow.”